- Client: UK National and Resident
- Net Worth: £5-10m
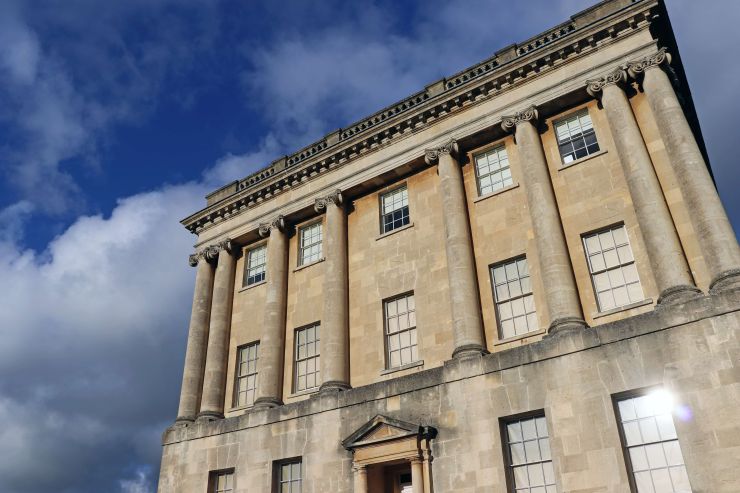
- Property: £1.4m Grade II listed, five-unit freehold property in Bath
- Loan: Six-month bridging loan to repay the existing bridge and extend the financing term
- Interest Rate: 0.86% PCM
Enness was approached by a UK-based client who owned a five-unit freehold property in Bath and needed to refinance an existing bridging facility that was approaching maturity. The property, valued at approximately £1.4 million, was a Grade II listed building that had undergone significant renovation and refurbishment works.
The client had originally used bridging finance to purchase and renovate the property, with two separate bridging facilities arranged during the project. The works involved completely stripping out and refurbishing the building, with the intention of significantly increasing its value and preparing the five units for their intended use.
However, the renovation took considerably longer than originally anticipated. External factors, including delays caused by the COVID-19 pandemic, affected the project timeline. As a result, the existing bridging facility was approaching maturity before the works could be completed, leaving the client with a requirement for a third consecutive bridging facility.
This presented a significant lending challenge. Bridging finance is generally intended as a short-term solution with a defined exit, often through the sale of a property or refinancing onto a longer-term mortgage. A third consecutive bridge therefore fell outside the typical lending profile for many providers, particularly where the existing project had already required extensions to its original timeline.
Enness reviewed the client’s circumstances and identified an opportunity to approach the existing bridging lender. The lender already understood the property, the client’s financial position and the reasons for the extended timeframe, providing relevant context when considering a further facility.
An initial review indicated that an internal refinance with the existing lender would have been priced at more than 1% per month. Rather than accepting those initial terms, Enness resubmitted the application and negotiated a new structure through the same lender. This resulted in a six-month bridging facility at 0.86% per month, allowing the client to repay the existing bridge and continue the refurbishment.
A clear exit strategy was particularly important. The client needed to demonstrate that the remaining works could be completed within the six-month term. Enness also explored longer-term refinancing options, providing the lender with additional information around the proposed exit. Offers were obtained for a term facility based on a projected gross development value of approximately £2 million and anticipated rental income of around £10,000 per month.
The new bridging facility gave the client additional time to complete the project without requiring an exit while the works were still underway. It also demonstrated the importance of reviewing existing lender relationships and considering alternative terms rather than assuming that an extension or refinance must be accepted on the initial terms offered.
This case demonstrates how specialist bridging finance can provide flexibility when a property development does not progress according to its original timetable. While consecutive bridging facilities are unusual and will not be appropriate for every project, a strong financial position, clear explanation for delays and credible exit strategy can be relevant factors when presenting a specialist lending application.
If your existing bridging facility is approaching maturity and your project requires additional time to reach its intended exit, Enness can assess your circumstances and explore suitable property development bridging finance options.
Important: Bridging finance is short-term borrowing and requires a credible and achievable exit strategy. Where repayment depends on completing refurbishment or development works, delays, unexpected costs or changes in property values may affect the anticipated exit and the overall cost of borrowing. The rate referenced in this case study relates to a specific transaction and is not indicative of current or future pricing.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business.
Property values can fall as well as rise, and you may not get back the amount originally invested. Property investments can be illiquid and may take time to sell. Where borrowing is used, your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.