
- Client: Jersey-based client
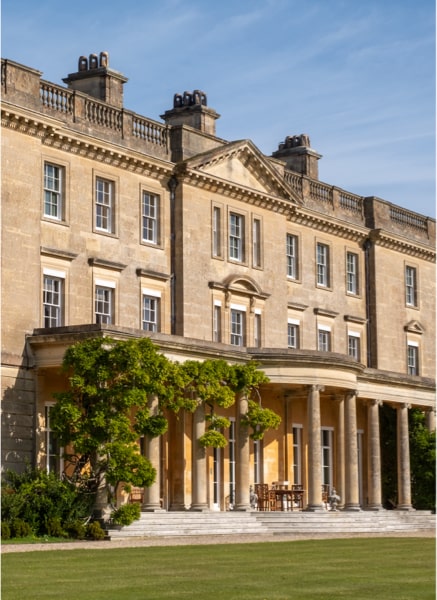
- Property: Freehold estate in Jersey
- Security value: £12M
- Loan amount: £7.2M
- Term: 12 months
- Margin: 8.5% p.a.
Enness was approached in relation to a £12M freehold estate in Jersey that was being marketed for sale under court order. The existing mortgage had expired, leaving the client requiring short-term finance to replace the outstanding debt and release funds for the trustees managing the estate.
The required facility was £7.2M against a security value of £12M. Given the size and circumstances of the loan, speed was an important consideration. The client needed a solution that could be arranged quickly while providing sufficient time for the property to be sold.
Large bridging transactions can involve multiple parties and moving parts, particularly where an existing facility has expired and the underlying property is already being marketed. In this case, identifying a lender with the appetite and ability to move within the required timeframe was central to the transaction.
Enness approached its network of specialist bridging lenders to create competition around the opportunity and negotiate suitable terms. A 12-month facility was secured at a margin of 8.5% per annum, with a 1.5% arrangement fee and 0.5% exit fee.
The facility provided the client with the liquidity required while the estate was being sold. Although the loan was structured for up to 12 months, the property was subsequently sold and the bridging facility repaid after seven months.
The case demonstrates how large bridging finance can provide a short-term solution where an existing mortgage has expired and a property is being prepared for sale. The appropriate structure will depend on the security, proposed exit strategy, borrower circumstances and lender criteria.
Enness works with specialist providers across the large bridging finance market, helping clients source funding for complex and time-sensitive transactions. Each facility is subject to lender assessment, valuation, due diligence and the specific circumstances of the transaction.
Important: Bridging finance is short-term borrowing and requires a credible and achievable exit strategy. Where repayment depends on the sale of a property, delays or changes in market conditions may affect the anticipated exit and the overall cost of borrowing. The terms referenced in this case study relate to a historical transaction and are not indicative of current or future pricing.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business.
Property values can fall as well as rise, and you may not get back the amount originally invested. Property investments can be illiquid and may take time to sell. Where borrowing is used, your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.