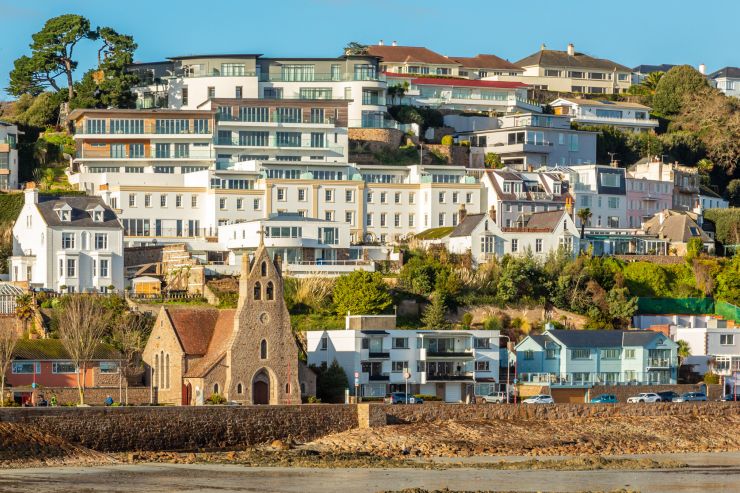
Enness was approached by a client looking to acquire a dilapidated property in Jersey with plans to secure planning consent and develop the site into a luxury private residence.
The client had negotiated a purchase price of £3.5M, with completion required within weeks of planning consent being granted. As the proposed loan was equal to the full purchase price, conventional lenders were unlikely to be suitable for the transaction.
The key challenge was finding a lender prepared to consider 100% of the purchase price while recognising the potential value created by the planning consent. The client also had previous experience in luxury property development, which provided important context when assessing the proposed project.
Enness approached specialist lenders with experience in acquisition and development finance and identified a lender willing to provide the full £3.5M required. The facility was structured over 15 months with interest retained, meaning the interest was incorporated into the facility rather than requiring monthly payments throughout the term.
The structure gave the client the time needed to progress the project following acquisition and work towards the proposed development. It also demonstrated the flexibility that can sometimes be available through specialist property finance where a transaction falls outside conventional lending criteria.
Development sites can present additional challenges for borrowers, particularly where planning consent is still being progressed or the property's existing condition makes conventional mortgage finance unsuitable. Lenders will typically consider factors including the current property, proposed development, planning position, borrower experience and intended exit strategy when assessing this type of transaction.
Enness works with specialist lenders across the property development finance market and can structure funding around acquisitions, planning-led opportunities and development projects. The appropriate financing structure will depend on the individual project, borrower profile, security and lender criteria.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business.
Property values can fall as well as rise, and you may not get back the amount originally invested. Property investments can be illiquid and may take time to sell. Where borrowing is used, your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.