Refinancing a French Villa to Release Capital for a Business Venture
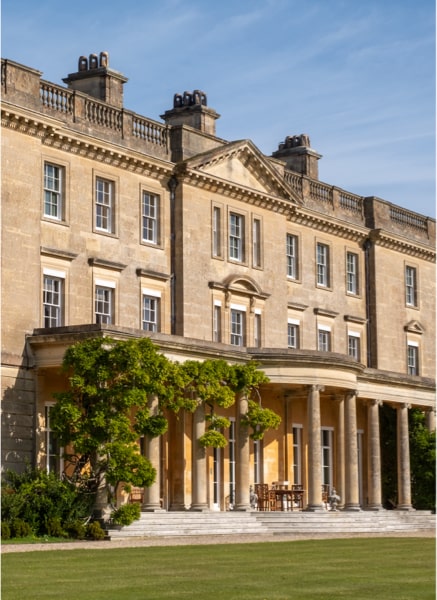
This case study explores how Enness Global considered a proposed circa €6 million mortgage refinance against a high-value French villa, with the aim of releasing capital for a business venture. The proposed structure involved interest-only borrowing alongside a new private banking relationship, with asset transfer timing forming a key part of the arrangement. Completion of the refinancing was not confirmed.
Borrowing secured against property carries a risk of repossession if repayments are not maintained. Interest-only borrowing does not reduce the outstanding capital, which must be repaid at the end of the term. Currency movements may also increase borrowing costs where the loan currency differs from the borrower's income or assets. Finance is subject to lender approval and individual circumstances.
Refinancing a French property can in some cases release equity to fund various goals, such as a business venture. This involves replacing existing borrowing with a larger mortgage. Enness Global helps high-net-worth property owners explore this capital-raising route, including private banking structures where assets under management form part of the arrangement. Eligibility depends on affordability, security and lender criteria.
Risk Warning: Your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it. Currency movements may increase your borrowing costs and outstanding debt when the loan currency differs from your income or assets.
Explore our French mortgage services, finance for entrepreneurs and business owners, and a related French Riviera refinancing case involving a later AUM transfer.
What Did the Client Want to Achieve?
The client wanted to replace the villa's existing mortgage, release additional capital for a new business venture and establish a new private banking relationship. The requirement therefore involved both property borrowing and the timing of asset transfers between banks. Enness considered the mortgage alongside the client's wider international asset position.
Why Did the Asset Transfer Make Refinancing More Complex?
Some assets remained with the existing lender and could only be transferred once its mortgage had been refinanced. The new bank therefore needed to accept the proposed assets-under-management relationship being established after refinancing, rather than requiring the full transfer before the mortgage could proceed. The challenge was coordinating two connected transactions in the right order.
How Did Enness Approach the Refinancing?
Enness approached a private bank willing to consider the client's wider finances and the proposed timing of the asset transfer. The proposed arrangement combined interest-only borrowing secured against the villa with an AUM relationship, subject to due diligence and lending criteria. Different borrowing amounts, currencies and AUM arrangements were considered.
What Does AUM Mean for a Property Owner?
Assets under management, or AUM, are assets a client places with a bank or investment manager under an agreed management arrangement. Some private banks link property lending to an AUM relationship. The required assets, transfer deadline, costs and ongoing obligations depend on the individual agreement.
A proposed asset transfer should be assessed alongside the mortgage. It can affect how much cash remains available for the business and what happens if the transfer is delayed.
“The timing of the asset transfer mattered as much as the mortgage. Both needed to work together for the proposed funding structure to proceed.”
Islay Robinson, CEO and Founder, Enness Global
What Does Current French Lending Data Show?
Banque de France reported on 9 February 2026 that housing loan production, excluding renegotiations, increased by 33 per cent in 2025 compared with 2024. This provides broader market context, but does not measure availability for high-value, business-purpose capital raising or bespoke private bank refinancing.
The figures relate to 2025. They do not describe market conditions when this historic case was originally published in 2017 or establish eligibility for a similar facility today.
What Are the Risks and What Could Go Differently?
Property-backed business funding puts the villa at risk if repayments are not maintained. An interest-only structure also leaves the principal to be repaid at the end of the term. The business venture may not generate the expected returns, while the mortgage and banking obligations remain due.
- Repayment Risk: The borrower needs a credible repayment plan that does not depend solely on the new venture succeeding.
- Currency Risk: Exchange-rate movements may increase repayments or the amount needed to repay the loan.
- Asset-Transfer Risk: Delays or restrictions could prevent the agreed AUM arrangement being established on time.
- Valuation Risk: A lower lender valuation could reduce the funds available.
- Net Proceeds: Repaying existing borrowing and covering transaction costs reduces the cash released.
- AUM Obligations: Management costs, minimum asset requirements and withdrawal restrictions need review.
- Timing and Approval: Underwriting, documentation and cross-border checks can delay or prevent funding.
The consequences of failing to meet an AUM commitment depend on the signed lending and banking agreements. They should be understood before proceeding.
Speak to a French Mortgage Specialist
For an initial discussion, provide your contact details, approximate funding requirement, property location and a short explanation of the existing borrowing and proposed use of funds.
Important Information
This historic case study illustrates a financing approach. It is not an offer of finance, a guarantee of availability or confirmation that a transaction completed.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business. Not all business completes, and the posting of a case study does not represent a completed piece of business.
Enness Global is a credit broker, not a lender. Finance is subject to status, underwriting, affordability, valuation, asset suitability, jurisdiction and lender criteria. Terms, borrowing currencies and AUM requirements vary between applicants and providers.
Property values can fall as well as rise. Property may take time to sell, and sale proceeds may not cover outstanding borrowing. Your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.
Interest-only borrowing requires repayment of the principal at the end of the term. Currency movements may increase borrowing costs and the outstanding debt where the loan currency differs from your income or assets.
Enness Global does not provide tax, investment, insurance or legal advice. Obtain advice from appropriately qualified professionals where required. Lending secured on property outside the UK may not be regulated by the FCA, and UK regulatory protections may not apply. The regulatory position applicable to the facility will be confirmed before you proceed.
Related Case Studies
See how Enness structures finance for offshore, commercial and high-value transactions.
View all
Frequently asked questions
Expert answers from our specialist brokers to the questions we are asked most often.
Let's talk nowCan I Release Equity from a French Villa Without Selling It?
Potentially. A capital-raising refinance may replace the existing mortgage with a larger loan, with the balance released after debt repayment and transaction costs. This is additional borrowing secured against the villa. It is subject to status, affordability, valuation and lender approval.