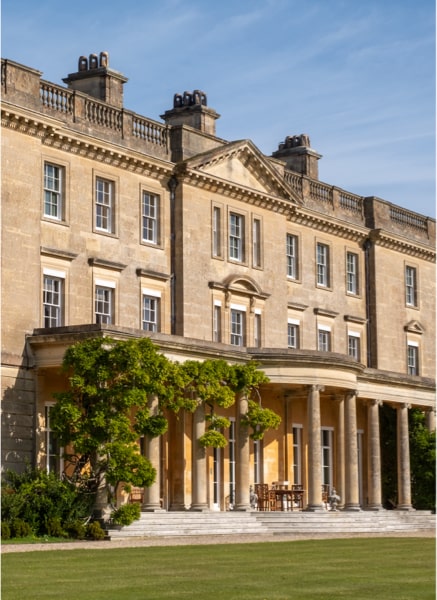
£9M Private Bank Refinance and Capital Raise for Central London Property Developer
Enness structured a proposed £9m private bank refinancing facility against two prime Central London investment properties valued at approximately £15m. The facility was designed to refinance around £7m of existing borrowing and provide a further £2m in capital for the client's property development activities. The proposed structure combined a private bank mortgage with an overdraft facility, taking account of the client's variable development income and substantial property holdings. Completion has not been independently confirmed.
Your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it. Borrowing against investment properties creates additional financial obligations, and property values can fall as well as rise. Overdraft facilities may be subject to variable interest rates, repayment on demand and periodic review. Mortgages secured against investment property held for business purposes, and business overdraft facilities, may not be regulated by the Financial Conduct Authority. Lending is subject to lender approval and the terms of the specific facility.
The Client and Their Objective
A property developer specialising in luxury residential projects approached Enness Global seeking to refinance existing borrowing secured against two prime Central London investment properties. The properties had a combined value of approximately £15m, with outstanding borrowing of around £7m. Alongside refinancing the existing debt, the client wanted to raise a further £2m to support their wider property development strategy.
The client had substantial wealth tied up in property, with a significant proportion of their capital committed to ongoing and future development projects. Although their underlying assets were valuable, their available liquidity was relatively limited, while income fluctuated according to the progress, completion and sale of individual developments.
The objective was to secure a refinancing arrangement that recognised the strength of the client's property portfolio and development experience, rather than relying exclusively on conventional income assessments. The client also required flexibility around the additional capital, allowing funds to be accessed in line with future property-related requirements.
Why Variable Income and Property-Concentrated Wealth Complicated Lending
The principal challenge was finding a lender willing to assess the client's financial position beyond their immediate income and available cash reserves. Although the client owned valuable investment properties, much of their wealth was concentrated in real estate rather than liquid assets, while their existing borrowing was already substantial.
For property developers, income can be irregular because returns are often generated when projects are completed or properties are sold. This can create difficulties with conventional mortgage affordability assessments, which generally place considerable emphasis on consistent, verifiable income and the borrower's ability to meet ongoing repayment obligations.
In this case, the client's variable income and relatively limited liquidity did not fully reflect the value of their underlying assets or their experience in the luxury residential development market. The existing £7m debt commitment also needed to be considered alongside the proposed additional borrowing, making the overall lending requirement more complex.
The client was not simply looking to replace an existing mortgage. They wanted to raise approximately £2m in additional capital while retaining sufficient flexibility to support future developments. A conventional refinancing structure might not have provided the same ability to access and deploy funds in line with the client's changing cash flow requirements.
The challenge was therefore identifying a lender prepared to consider the wider property portfolio, the client's development track record and their overall financial position when assessing both the refinance and the additional capital requirement.
How Enness Structured the £9M Private Bank Refinance
Enness approached a specialist private bank mortgage lender experienced in assessing high-net-worth property investors and developers with complex financial circumstances. Rather than presenting the application solely around the client's variable income and existing borrowing, we focused on the strength of the underlying Central London properties, their combined value and the client's wider development experience.
The lender was able to consider the client's property holdings and overall financial position as part of its assessment, providing an alternative to a conventional mortgage application based primarily on regular income.
Enness structured a proposed bespoke refinancing arrangement totalling approximately £9m against the two investment properties, representing around 60% of their combined £15m value. The proposed facility incorporated a mortgage alongside an additional overdraft facility, allowing the client to refinance approximately £7m of existing borrowing while accessing a further £2m for property-related requirements.
The combination of secured mortgage borrowing and an overdraft facility was particularly relevant to the client's development-focused business model. While the mortgage provided the principal refinancing component, the overdraft offered additional flexibility around the use and timing of the extra capital, subject to the facility's agreed terms and conditions.
This approach was designed to accommodate the client's variable cash flow and provide access to capital without requiring them to sell existing property assets to generate liquidity.
The proposed structure was designed to address two requirements within a single private banking relationship: refinancing the existing debt secured against the Central London properties and providing additional funding to support the client's wider development strategy.
This case demonstrates the importance of specialist lender selection when refinancing substantial property portfolios, particularly where a borrower's wealth is concentrated in development assets and income fluctuates between projects. A client may have considerable underlying assets but still face difficulties meeting conventional lending criteria if their income and liquidity do not follow a predictable pattern.
By presenting the client's wider financial position and property development experience to a suitable private bank, Enness identified a refinancing structure that combined long-term secured borrowing with more flexible access to additional capital. The case also highlights how private banking facilities can be tailored to the financing requirements of experienced property investors and developers, subject to individual lender criteria and affordability assessments.
Speak to Enness Global
If you are looking to refinance a high-value property portfolio, raise additional capital or explore private bank mortgage options, Enness Global can help you assess the financing structures available.
We work with private banks and specialist lenders experienced in complex income arrangements, substantial property portfolios and high-value residential investment finance. Facing a similar lending requirement? Speak to an Enness adviser about your options.
Important Information
This case study reflects the circumstances of the client involved and is not representative of typical lending outcomes. The financing structure described is subject to lender criteria, affordability assessments, property valuation, legal due diligence and any applicable credit approval requirements. Completion of the facility has not been independently confirmed.
Your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it. Borrowing against investment properties creates additional financial obligations, and property values can fall as well as rise.
Mortgages secured against investment property held for business purposes, and business overdraft facilities, may not be regulated by the Financial Conduct Authority.
Overdraft facilities may be subject to variable interest rates, repayment on demand, periodic review or other conditions depending on the lender's terms. The availability of additional borrowing and the flexibility to access funds are subject to the specific facility agreement.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only. Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business. Nothing in this case study constitutes financial, investment, legal or tax advice.
Related Case Studies
See how Enness structures finance for offshore, commercial and high-value transactions.
View all
Frequently asked questions
Expert answers from our specialist brokers to the questions we are asked most often.
Let's talk nowCan a Property Developer Refinance Multiple Investment Properties?
Yes. Private banks may consider refinancing facilities secured against multiple investment properties, depending on the portfolio's value, existing borrowing and the borrower's wider financial position.