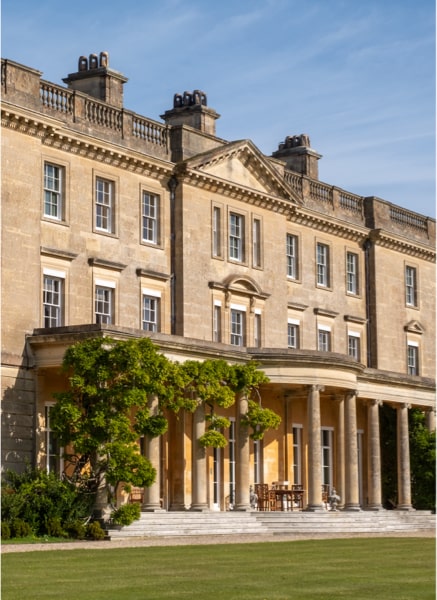
£3M Holiday Let Remortgage on a £5M Luxury Property
A £3m private bank remortgage was arranged against a refurbished luxury countryside holiday let valued at £5m. The refinancing replaced existing bridging finance and allowed the owner to generate holiday rental income while retaining the flexibility to use the property personally. The mortgage was completed at 60% loan-to-value, with no early repayment charges and unlimited overpayments under the agreed terms.
Your property may be repossessed if you do not keep up repayments on your mortgage or other loan secured against it. Rental income from a holiday let is not guaranteed and may vary depending on occupancy, seasonality and demand. Property values can fall, and you may not recover the amount originally invested. Lending is subject to lender approval and may not be suitable for every borrower or circumstance.
Summary and Key Metrics
| Key Metric | Starting Position | Structured Outcome |
|---|---|---|
| Asset Value and Type | £5m luxury countryside holiday let | Refurbished property refinanced |
| Capital Required | £3m to refinance existing bridging finance | £3m remortgage completed |
| Lending Structure | Traditional holiday let affordability criteria could not support the required borrowing | Private bank mortgage assessed against wider income and liquidity |
| Loan-to-Value | £3m against a £5m property | 60% LTV |
| Flexibility | Personal occupation restrictions with some lenders | Personal use permitted under the agreed terms |
| Repayment Terms | Long-term financing required following refurbishment | No early repayment charges and unlimited overpayments |
The Client and Their Objective
Having completed an extensive refurbishment of a luxury countryside holiday let property valued at £5m, the client approached Enness to arrange a £3m remortgage.
Enness had previously secured bridging finance to fund the property's refurbishment. With the works complete, the next step was to refinance the short-term borrowing onto a longer-term mortgage that better suited the client's plans for the property.
However, this was not a conventional holiday let investment. While the client intended to generate rental income, they also wanted the freedom to enjoy the property personally at various points throughout the year. The objective was therefore to secure a high-value holiday let mortgage that could accommodate both the property's rental potential and the client's lifestyle requirements, without restrictive repayment conditions.
Why Traditional Holiday Let Lenders Could Not Accommodate the Borrowing
Securing a £3m holiday let mortgage presented several challenges. Many traditional holiday let lenders cap their maximum loan sizes below this level, making the client's borrowing requirement difficult to accommodate through conventional lending channels.
Affordability was another obstacle. Holiday let lenders typically assess borrowing capacity against anticipated rental income, often applying stress tests to account for potential changes in interest rates and rental occupancy.
Although the property had undergone a full refurbishment, the rental income alone did not satisfy the affordability requirements for the amount requested. The client's intention to occupy the property personally added another consideration. Some holiday let lenders impose restrictions on owner occupation, which would have limited the flexibility the client wanted.
The challenge was not simply finding a lender prepared to offer a larger mortgage. It was identifying one willing to consider the client's wider financial circumstances while accommodating both personal use and commercial holiday letting.
How Enness Structured the £3M Holiday Let Remortgage
Enness approached a private bank with which it had an established lending relationship, presenting the client's wider financial position alongside the property's rental potential.
Rather than assessing affordability solely against projected holiday let income, Enness demonstrated that the client had sufficient personal income and liquidity to support mortgage repayments during periods without rental income. This also provided reassurance that the client could meet their obligations should borrowing costs increase.
By considering the client's overall financial position, the private bank was able to assess the borrowing on a broader basis than traditional holiday let lenders. The result was a £3m remortgage against the £5m property, representing 60% LTV.
Crucially, the agreed mortgage structure also addressed the client's requirements for flexibility. The facility carried no early repayment charges and allowed unlimited overpayments. The terms also accommodated the client's intention to generate holiday rental income while retaining the ability to use the property personally, subject to the agreed mortgage conditions.
With the refurbishment complete and the bridging finance refinanced, the client secured a longer-term borrowing arrangement aligned with their financial position and intended use of the property. These terms were specific to this client's circumstances and market conditions at the time, and are not indicative of terms available to other borrowers.
This case demonstrates how a private bank's broader approach to affordability can provide an alternative where conventional holiday let lending criteria do not accommodate a high-value borrowing requirement. You can also read about a high-value holiday let refinancing and refurbishment facility arranged by Enness.
Speak to Enness About Your Holiday Let Mortgage
Whether you are refinancing an existing holiday let, purchasing a luxury rental property or looking to replace short-term bridging finance, Enness can help explore your financing options.
Our advisers work with over 1,000 lenders, including private banks and specialist mortgage providers, to identify lenders willing to consider complex and high-value borrowing requirements. If you are facing a similar lending requirement, speak to an Enness mortgage specialist about your options.
Important Information
Your home may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Property values can fall as well as rise. Rental income from a holiday let is not guaranteed and may vary with occupancy, seasonality and demand.
Bridging finance is short-term borrowing secured against property and may not be suitable for your circumstances. The loan size, loan-to-value and repayment terms described were specific to this client and market conditions at the time, and are not indicative of terms available to other borrowers. All lending is subject to status and lender criteria.
Related Case Studies
See how Enness structures finance for offshore, commercial and high-value transactions.
View all
Frequently asked questions
Expert answers from our specialist brokers to the questions we are asked most often.
Let's talk nowCan You Get a £3 Million Mortgage on a Holiday Let Property?
A £3m holiday let mortgage may be available through private banks or specialist lenders, depending on the property's value, the borrower's financial circumstances and the intended use. Many conventional holiday let lenders have lower maximum loan sizes. Enness works with over 1,000 lenders to explore suitable financing options for high-value properties.