How Can Bridge-to-Let Finance Fund a Residential Conversion?
A bridge-to-let loan can help property investors acquire and improve a property before refinancing onto longer-term borrowing once the asset is ready to let. Enness Global arranges bridge-to-let finance for property investors who need short-term funding for acquisitions, conversions or refurbishments before moving onto a longer-term facility.
Bridging finance is subject to status, valuation, lender credit approval and legal due diligence. Your property may be repossessed if you do not keep up repayments on a mortgage or other debt secured on it.
Why Did the Property Investor Need Bridge-to-Let Finance?
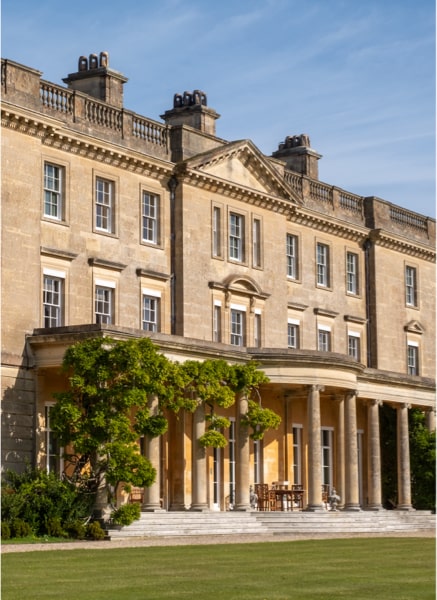
The property investor needed bridge-to-let finance to acquire a vacant period building and convert it into residential apartments before moving onto longer-term investment finance. The property required significant reconfiguration and modernisation, meaning conventional buy-to-let finance was not suitable at the point of acquisition.
The opportunity was also time-sensitive, with interest from other prospective buyers and a seller looking for a buyer able to progress.
A standard mortgage was not appropriate because the property was vacant, was not generating residential rental income and required substantial works before it could meet conventional long-term lending criteria.
Bridge-to-let finance was therefore considered as a way to fund the acquisition while giving the investor time to complete the planned conversion and establish a lettable residential asset.
The requirement also shared characteristics with refurbishment bridging finance, which can be used for transitional properties requiring significant renovation or commercial-to-residential conversion before longer-term refinancing.
For a related example of short-term funding supporting refurbishment before an intended refinance, see our property refurbishment bridging finance case study.
What Made the Residential Conversion More Complex to Finance?
The conversion was more complex to finance because the property was vacant, previously used for commercial purposes and required extensive works before it could generate residential rental income. The funding therefore needed to account for the asset in its existing condition as well as the investor's proposed refurbishment and exit strategy.
Rather than assessing the property as a completed rental investment, the financing needed to consider the proposed works, the client's experience, anticipated rental demand and the viability of refinancing once the apartments were complete and let.
This reflects wider activity in the UK bridging market. Bridging Trends reported that investment purchases represented 20 per cent of bridging transactions in 2025, while heavy refurbishment increased from nine per cent in 2024 to 11 per cent in 2025.
Islay Robinson, Group CEO of Enness Global, stated "The challenge was finding a lender willing to look beyond the property’s vacant, commercial condition and understand what the asset could become. The strength of the refurbishment plan, the client’s experience and a credible refinance strategy were therefore central to the funding case.”
How Was the Bridge-to-Let Finance Structured?
The bridge-to-let finance was structured to provide circa £6.4 million of short-term borrowing against the property, subject to status and lender approval. The proposed structure gave the investor time to acquire the asset, complete the planned works and move towards a longer-term refinancing strategy.
The assessment considered factors including the existing property, proposed refurbishment programme, projected rental demand and the investor's previous property experience.
The short-term nature of the finance was particularly important. Rather than requiring the property to satisfy long-term buy-to-let criteria immediately, the structure was intended to provide a transitional period in which the asset could be repositioned for residential use.
No current rate, fee or loan-to-value is implied by this case. Terms for bridge-to-let finance depend on the property, borrower, proposed works, exit strategy and lender assessment at the time of application.
How Did the Refurbishment Support the Investor's Rental Strategy?
The refurbishment strategy was designed to reposition a vacant commercial property as a collection of residential rental apartments. The proposed works included internal reconfiguration and modernisation, with the objective of creating accommodation suitable for the long-term rental market.
The plans involved retaining appropriate period characteristics while modernising the interiors and improving the wider building.
Communal and external areas also formed part of the proposed improvements, with the overall strategy focused on creating a stronger residential proposition for prospective tenants.
Establishing rental income was an important part of the planned transition from short-term bridging finance to longer-term investment borrowing.
What Was the Exit Strategy for the Bridge-to-Let Loan?
The primary exit strategy was to refinance onto longer-term investment finance once the conversion was complete, the apartments had been valued and a stable rental profile had been established. A secondary potential exit involved selling selected apartments if appropriate market conditions supported individual disposals.
Having a credible exit strategy is an important consideration in bridge-to-let finance because bridging is short-term borrowing.
In this case, the proposed refinancing route depended on the completed property meeting the requirements of a long-term lender, including valuation, rental income and borrower criteria at that time.
Refinancing is not guaranteed, even where it forms the intended exit at the beginning of a bridging transaction.
What Were the Risks and What Could Have Gone Differently?
The bridge-to-let strategy depended on the refurbishment progressing as planned, sufficient rental demand being established and longer-term refinancing remaining available. Delays, cost overruns, weaker rental demand, valuation changes or changes to lender criteria could have affected the proposed exit and increased the overall cost of borrowing.
Conversion projects can also encounter unexpected issues during the works. These may affect both the project timetable and the point at which a property becomes suitable for letting or refinancing.
Where refinancing forms the primary exit, the completed property's valuation and rental profile will need to satisfy the requirements of the relevant lender at that time.
The secondary disposal strategy would also have been exposed to property market conditions. A slower sales market or lower-than-anticipated valuations could have affected the timing or viability of that exit.
When Can Bridge-to-Let Finance Be Used by Property Investors?
Bridge-to-let finance can be used by property investors who need short-term funding to acquire or improve a property before it becomes suitable for longer-term rental finance. It can be particularly relevant where a property is vacant, requires refurbishment or conversion, or does not initially meet conventional buy-to-let lending criteria.
Potential situations include:
- Acquiring a property that is not yet suitable for a conventional mortgage
- Completing refurbishment before refinancing
- Converting commercial space for residential use
- Purchasing a vacant investment property
- Improving a property's condition before letting
- Establishing rental income before applying for longer-term finance
The appropriate structure will depend on the individual property, borrower, works and proposed exit, and all finance is subject to status and lender approval.
Important Information
This case study reflects one client’s circumstances and is not representative of typical outcomes. Terms are subject to lender credit approval, valuation and legal due diligence and may be withdrawn or amended by the lender at any time. As with any lending secured against property, your property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
Nothing in this article constitutes financial, legal or tax advice.
Related Case Studies
See how Enness structures finance for offshore, commercial and high-value transactions.
View all
Frequently asked questions
Expert answers from our specialist brokers to the questions we are asked most often.
Let's talk nowWhat is a bridge-to-let loan?
A bridge-to-let loan is a form of short-term property finance intended to bridge the period between acquiring or improving a property and moving onto longer-term rental finance. The intended refinance is normally considered as part of the exit strategy from the outset.