- Client: European real estate investor
- Property Location: Central Italy
- Property Value: Approximately €7 million
- Loan-to-Value: Approximately 50%
- Term: One year, with an option to extend
- Purpose: Acquisition of additional real estate
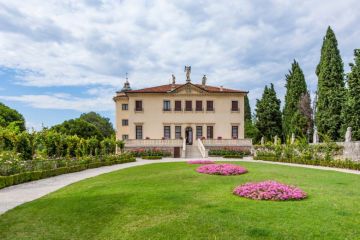
Enness was approached by an experienced European real estate investor looking to release capital from a property they owned in central Italy. The property had been purchased for approximately €7 million several years earlier and was being used as an investment asset, generating income through a combination of holiday lets, events and exhibitions.
Unlike the client’s other properties, which were already leveraged, this particular asset had no existing borrowing against it. The client wanted to make use of that available equity to fund further real estate acquisitions.
The timing of the transaction was important. The client had already agreed the sale of other assets within their portfolio, with completion expected within the following few months. The proceeds from those sales were intended to provide the exit for the proposed short-term facility.
Finding suitable bridging finance against an Italian property presented a challenge. Local lending requirements and the administrative processes involved meant that the client needed a lender able to consider the asset, jurisdiction and proposed exit strategy.
Enness identified a lender willing to provide funding at approximately 50% LTV, structured across two tranches. The facility was arranged for an initial 12-month term with the option to extend for a further year, providing additional flexibility should the planned asset sales take longer than expected.
As the client expected to repay the borrowing within a few months, the early repayment terms were particularly important. The structure allowed the early repayment charge to apply only during the initial period of the facility. This meant the client could repay the borrowing following the anticipated asset sales without being committed to a longer-term financing arrangement.
The facility was arranged at an interest rate of approximately 1% per month, compared with alternative terms the client had received ranging from approximately 1.15% to 1.5% per month. The transaction was completed within a matter of weeks, allowing the client to release equity from their Italian property to support their wider investment plans.
The case demonstrates the importance of taking an international approach to property finance when assets are held across different jurisdictions. Local market conditions, lending appetite, legal processes and the proposed exit can all influence the availability and structure of finance.
For investors looking to release capital from international property to fund further acquisitions, speak to a mortgage specialist to discuss your requirements.
Important: Bridging finance is short-term borrowing and requires a credible and achievable repayment or exit strategy. Where repayment depends on the sale of other assets, delays or changes in market conditions may affect the anticipated exit and the overall cost of borrowing. International property transactions may also involve additional legal, tax, currency and regulatory considerations. The terms referenced in this case study relate to a specific transaction and are not indicative of current or future pricing.
Read the UK version of this case study.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business.
Property values can fall as well as rise, and you may not get back the amount originally invested. Property investments can be illiquid and may take time to sell. Where borrowing is used, your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.