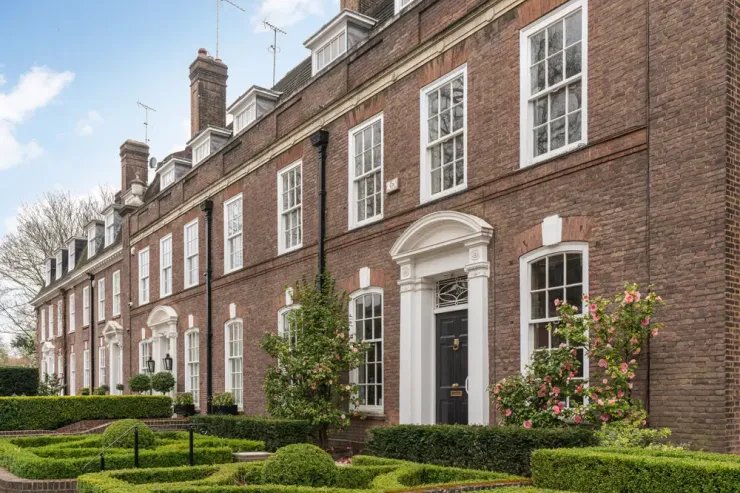
- Property Location: London
- Property Value: Circa £11.5 million
- Loan Amount: Circa £5 million
- Interest Rate: Subject to lender terms
- Purpose: Refinance existing equity release facility and raise additional capital
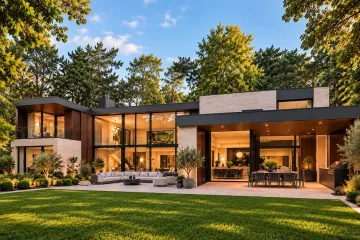
Enness was approached by a high-net-worth individual who owned a London property valued at approximately £11.5 million. With the majority of the client’s wealth tied to the property, they wanted to raise additional capital while the property was being marketed for sale.
The property already had an existing equity release/lifetime mortgage facility secured against it. However, the client was unable to raise any further funds through the existing arrangement. The requirement was therefore twofold: refinance the existing facility and release additional equity on a short-term basis while allowing the property sale to progress.
The main challenge was finding a lender that could accommodate the existing facility, the additional capital requirement and the client’s circumstances within a short-term structure. The new financing also needed to provide flexibility around the anticipated sale of the property.
Enness identified a suitable short-term financing solution and worked through the underwriting and legal requirements with the lender. Approximately one week before completion, an unexpected issue arose that had the potential to delay the transaction. Given the purpose of the facility, any significant delay could have affected the intended financing strategy.
Enness worked with the relevant parties to address the lender’s concerns and resolve the issue. The matter was dealt with without delaying the intended completion, allowing the transaction to proceed within the required timeframe.
Enness secured a circa £5 million facility, with the interest rate subject to the agreed lender terms. The structure enabled the existing equity release/lifetime mortgage to be refinanced while providing the client with the additional capital they required as the property sale progressed.
This case demonstrates how equity release and property equity solutions can form part of a wider financing strategy, particularly where an existing facility no longer provides sufficient flexibility. In situations where capital is required for a defined period while a property is being sold, bridging finance may also provide an alternative short-term structure, subject to the property, exit strategy and lender criteria.
For high-net-worth clients with significant equity in a property who need to refinance an existing facility or release additional capital, Enness can assess the wider circumstances and explore suitable financing structures.
If you are considering releasing equity from a high-value property or need short-term finance while an asset is being sold, speak to a mortgage specialist to discuss your requirements.
Important: Short-term property finance is intended for a defined period and requires a credible and achievable repayment or exit strategy. Where repayment depends on the sale of a property, delays, changes in property values or market conditions may affect the anticipated exit and the overall cost of borrowing. The terms and availability of any facility are subject to lender criteria and individual circumstances.
Read the UK version of this case study.
Information contained in our case studies is for market and illustrative purposes only. In some cases, these may be made up of multiple cases and are for illustrative purposes only.
Some case studies are made up of enquiries that have come into the business, not all business completes, and the posting of a case study does not represent a completed piece of business.
Property values can fall as well as rise, and you may not get back the amount originally invested. Property investments can be illiquid and may take time to sell. Where borrowing is used, your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured against it.